How Foreign Companies Are Taxed in India: A Complete Guide
Foreign companies pay tax in India at 35%, not 40%. Here are the current rates, how permanent establishment works, the branch versus subsidiary comparison, and what you must file.
Foreign companies pay tax in India at 35%, not 40%. Here are the current rates, how permanent establishment works, the branch versus subsidiary comparison, and what you must file.
Planning to expand into India? Before you model anything, get the headline number right, because a lot of published guidance still has it wrong.
A foreign company is taxed in India at a base rate of 35 per cent, not 40. The Finance (No. 2) Act, 2024 cut the rate by five percentage points with effect from assessment year 2025-26, and the Income-tax Act, 2025 has retained it. With surcharge and cess, the effective rate runs between 36.40 and 38.22 per cent depending on income.
This guide covers what India actually taxes, at what rate, how permanent establishment changes the answer, how a branch compares with a subsidiary, and what you have to file.
A foreign company is one incorporated outside India that has not made the prescribed arrangements for declaring and paying dividends within India out of its Indian income.
Incorporation abroad is not the end of the enquiry, though. If the key management and commercial decisions for that company are in substance made from India, India can treat it as resident and tax its worldwide income under the place of effective management test. That applies only where turnover exceeds ₹50 crore, and it is set out fully in our guide to POEM and tax in India.
An experienced tax consultant in Gurgaon can guide you in understanding these rules and help you pay the right taxes.
You’ll also be considered taxable in India if you have a place of business, employees, digital presence, or assets in India.
If you're a foreign company doing business in India, only the income that arises in India is taxed. That includes:
Income earned outside India is not taxed here — unless it’s connected to your Indian operations.
Absent residence, only income that arises in or is connected to India is taxed. Typically:
Income earned wholly outside India, unconnected to Indian operations, is not taxed here.
Yes, that’s higher than what Indian companies pay. But with the right planning and advice from a trusted CA firm in Gurgaon, you can legally reduce your tax load and keep more profits in your pocket.
Must Read: Input Tax Credit (ITC) Issues for Exporters with Foreign Expenses

Surcharge: nil up to ₹1 crore, 2% between ₹1 crore and ₹10 crore, 5% above ₹10 crore, with marginal relief available.
Health and education cess: 4% on tax plus surcharge.

Minimum Alternate Tax. MAT applies where normal tax is below the MAT threshold on book profit. The Finance Act, 2026 reduced the MAT rate from 15% to 14% with effect from 1 April 2026. Critically, MAT does not apply to a foreign company from a treaty country with no PE in India, or from a non-treaty country not required to register here.
Not every foreign company sets up a full office in India right away. Here are a few common ways foreign businesses operate, and how they're taxed:
You’re just here for communication, networking, or market research — not to earn money.
No taxes, but you must register and file annual returns.
You’re carrying out actual business in India — maybe a contract or project.
Taxed like a foreign company at 40% on profits earned in India.
This is the most popular route.
It’s treated as an Indian company and taxed at 25% or 22% — much lower!
Recommended: How to Set Up a Liaison Office in India – Step By Step Process
This is the single most consequential structuring decision, and most guidance skips the arithmetic.

The gap between a branch at 38.22% and a subsidiary on the concessional regime at 25.17% is around 13 percentage points. That is the number to model before you choose a route, alongside repatriation cost and compliance burden.
With a PE, you are taxed on profits attributable to it. Without one, you may face only withholding on specific payments.
PE arises through a fixed place of business, a dependent agent habitually concluding contracts, a service PE created by employees or secondees present in India, or a construction or project site exceeding treaty thresholds. Expanded business connection provisions also reach non-residents with no physical presence, so the traditional fixed-place analysis is no longer sufficient on its own.
Two practical points. Secondees paid by the parent and cross-charged to India are the most common service PE trigger. And a liaison office that negotiates or concludes anything has stopped being a liaison office.
For the dispute route and how PE is defended, see who can advise on permanent establishment and international tax issues.
Where an Indian company pays a foreign company, it must deduct tax before remitting. Indicative statutory rates, all subject to treaty override:

Two things determine whether you get the treaty rate. A valid Tax Residency Certificate with Form 10F and a no-PE declaration, held before the remittance. And a PAN, without which the higher rate under Section 206AA can override the treaty rate.
The certification itself, Form 15CB, can only be issued by a chartered accountant. Our guide on who can advise on withholding tax for cross-border payments covers the process and the liability, which sits with the Indian payer rather than with you.
Yes — if you are a resident in India or your company has a Permanent Establishment (PE) in India, then your global income is taxable in India.
So even if your business earns income earned outside India, like income from a foreign source, it may still be taxable in India.
Here’s a simple way to look at it:
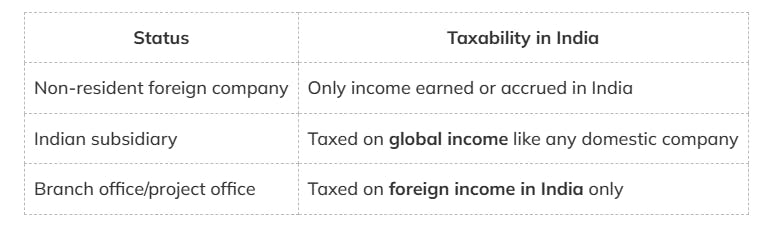
If your foreign income is also taxed in a foreign country, you can claim a foreign tax credit in India.
India offers foreign tax credit relief to avoid the issue of paying tax on the same income twice — once abroad and again in India. According to Rule 128 of the Income Tax Rules, foreign companies and individuals can claim foreign tax credit in India on taxes paid in a foreign country.
So, if your company has income earned outside India but you’re a tax resident in India, don’t worry — FTC can help lower your tax payable in India.
To claim it, you must:
Foreign tax credit is available only in the year in which the foreign tax was paid.
India has signed the Double Tax Avoidance Agreement with more than 90 countries. This ensures you don’t pay income tax on foreign income twice.
Under DTAA:
Just make sure you get a Tax Residency Certificate (TRC) from your home country and file it along with your ITR.
TDS means Tax Deducted at Source. If an Indian company pays you (a foreign business) for services, interest, or royalties, they’ll deduct tax before sending the money.
Here are some common TDS rates (can be lower with DTAA):
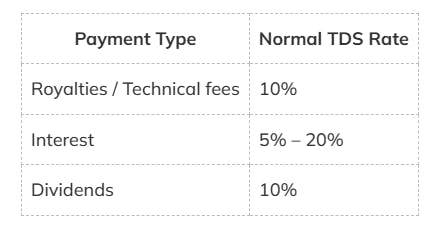
Always clarify TDS in your contracts so there are no surprises!
Yes — if you’re dealing with related parties, such as your Indian subsidiary, parent company, or group entities. Under Transfer Pricing, all prices must be set at arm’s length — just like how unrelated businesses would deal.
You’ll also need to:
Incorrect pricing can attract penalties — so don’t take this lightly.
Any transaction with your Indian subsidiary, parent or group companies must be at arm's length. You must maintain documentation and file Form 3CEB, certified by a chartered accountant.
Get this wrong and the adjustment lands as an addition to income, with penalty exposure and, because a TPO variation makes you an eligible assessee, a mandatory draft order route. Start with transfer pricing study report applicability, documentation requirements and how to build a defensible transfer pricing file.
This is an important term in international tax.
A Permanent Establishment (PE) means you have a fixed presence in India — like a branch, office, or even employees working for a long period. If you have a PE, you’ll be taxed on your total profits in India.
If you don’t have a PE, you may only pay a small withholding tax — which is a huge plus!
If you're offering goods or services in India, you may be affected by GST:
DSRV Tip: Ensure you follow GST rules properly to avoid penalties or delays in operations.
If you have foreign assets or income, you need to file your ITR carefully and disclose everything — even income earned by that person in a foreign country that may not be taxed locally.
Steps to follow:
Not filing these details properly may result in penalties or rejection of your FTC claim.
Even if the income is not taxable in India due to DTAA, it must be reported.
If any of the above are received by a person or business that is a resident in India, they must pay tax in India — unless covered under DTAA.
Here’s what your company might need to stay compliant in India:
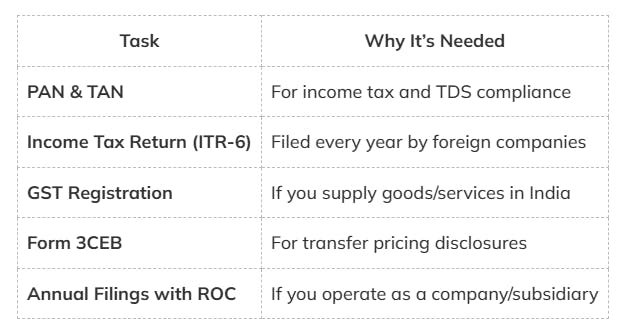
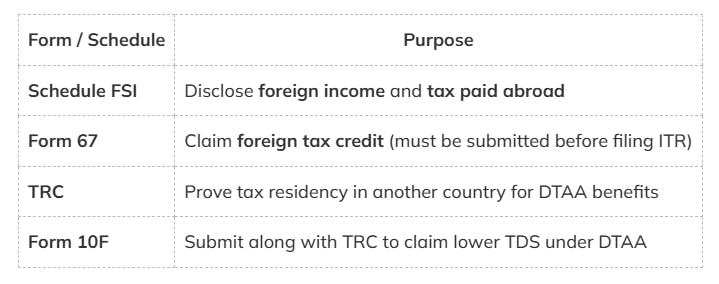
If you forget to file Form 67, or do not report details of your foreign income, you may:
💡 That’s why it’s best to speak to tax experts who understand both Indian and international tax systems.
A point almost no guidance mentions, and it matters enormously.
A foreign company is an eligible assessee under Section 275 of the Income-tax Act, 2025, formerly Section 144C. So the Assessing Officer cannot pass a final order against you straight away. He must first issue a draft order, and you then have thirty days to either accept it or file objections with the Dispute Resolution Panel.
That election is irreversible and it decides your entire dispute path. The DRP route means no demand crystallises while the panel is hearing you, it runs to a nine-month statutory clock, and it can consider material never placed before the Assessing Officer. See our guide to the Dispute Resolution Panel in income tax.
Foreign companies attract scrutiny on PE existence, profit attribution, treaty eligibility and transfer pricing, in that order of frequency.
The reply is where the case is decided, and the draft order route above means you have a genuine strategic choice early. Where the defect is procedural, a hearing denied or approval missing, a writ may be faster than an appeal, as set out in our note on writ versus appeal in tax litigation. Where it proceeds, the path runs through the first appeal and the Tribunal, which is the last forum that examines facts.
At DSRV India, we regularly help clients:
Our chartered accountants in Gurgaon are well-versed in the challenges faced by foreign companies and residents with overseas income.
DSRV and Co LLP advises foreign companies on entry structuring, PE risk, withholding and treaty positions, transfer pricing, and Indian compliance, and represents clients before the DRP and the Tribunal as part of our tax litigation and cross-border practice.
We have been in practice since 1987 from Gurugram, and we work regularly with Indian subsidiaries of foreign groups across Delhi NCR.
Get the rate right, then get the structure right. In that order.
Send us your proposed India structure or your existing India numbers. We will model branch versus subsidiary on effective tax cost, flag your PE exposure, and tell you what you will actually file.
India’s tax laws can feel overwhelming, especially when you’re dealing with foreign income, global assets, or foreign tax paid. But with the right planning and guidance, you can reduce your tax payable, stay compliant, and run your business smoothly.
Whether your income is taxable in India or taxed in a foreign country, it’s important to file everything accurately — and on time.
35 per cent base, reduced from 40 per cent by the Finance (No. 2) Act, 2024 with effect from AY 2025-26. With surcharge and cess the effective rate is 36.40 to 38.22 per cent.
No. The concessional regimes are available only to domestic companies. An Indian subsidiary can use them, a branch cannot.
On rate alone, a subsidiary, by roughly 13 percentage points at the top slab. Repatriation, compliance and commercial factors also matter, so model the whole picture.
Generally you face withholding on specific payments rather than tax on business profits. Treaty rates apply if you hold a valid TRC, Form 10F and a PAN.
Not if you are from a treaty country with no PE in India, or a non-treaty country not required to register here. The MAT rate itself reduced to 14 per cent from 1 April 2026.
Yes if you have a PE or income taxable here. Also yes, mandatorily, if you claim a treaty rate lower than the statutory rate, even where you would otherwise be exempt.
Because a foreign company is an eligible assessee, so a draft order must be issued first, giving you thirty days t
Contact DSRV India today — we’re here to make foreign taxation simple, smart, and stress-free.
Missed a tax appeal deadline? Get every GST and income tax appeal time limit, form, fee and pre-deposit rule for 2026 in one simple checklist.

Received a GST summons under Section 70? Know what officers can and cannot do, your rights during questioning, and how to prepare before you attend.

The Gujarat High Court struck down the 1% valuation floor on corporate guarantees and barred retrospective demands. What Torrent Power means for your group.
